As we head into the holidays, we want to say thank you. Your trust means everything to us, and we’re honored to be your 1031 exchange partner. Wishing you and yours a wonderful Thanksgiving. 🦃
Tax Straddling: The Year-End Timing Question Most Investors Never Ask
Sell investment property in Q4 and your 1031 exchange will almost certainly run past December 31. Most clients see that as a complication. Sometimes it’s the opposite.
When your 1031 exchange spans two tax years and your qualified intermediary disburses exchange funds to you in the second year, either as boot or because the exchange failed, the IRS treats that cash as received in the year you received it (or have the right to receive it), not the year you sold your relinquished property. Under IRC Section 453’s installment sale rules, where your relinquished property sale closed in 2026, cash boot received in January 2027 (or later) goes on your 2027 return that you’ll file in 2028, not on your 2026 return. One extra year, and no penalty for the attempted exchange.
This is tax straddling. A complete exchange defers everything – same as always. But a partial or failed exchange that crosses two tax years may still defer gain on the boot. This treatment is available for taxpayers who entered the exchange with genuine intent to complete it, even if the exchange ultimately falls short. This works if your exchange period itself runs into 2027. A QI can’t hold funds past day 180 to shift the tax year.
One thing worth flagging: gain from a mortgage payoff on the relinquished property that was not replaced in the exchange doesn’t follow the same rule. That debt relief boot is recognized in the year of the relinquished property sale. If your exchange will straddle two tax years and you may end up with boot or a failed exchange, run the numbers with your tax advisor before year-end.
Webinar: 1031 Tax-Deferred Exchanges
For Commercial Real Estate Brokers
Wednesday, December 2
11:00 AM – 1:00 PM PT
CE Credit Available
This two-hour course for commercial brokers provides a concise and thorough overview of 1031 exchanges. This webinar tackles advanced issues such as partnership/LLC scenarios, creative property variations such as perpetual cellular easements (cell towers), fractional ownership, transferable development rights, reverse and improvement exchanges, how to avoid common pitfalls and related-party transactions.
Webinar: 1031 Exchange Issues in Today’s Market
For CPAs & Tax Advisors
Monday, December 14th
2:00 PM – 3:00 PM PST
CPE Credit Available
This one-hour intermediate/advanced webinar provides a concise and thorough overview of 1031 exchanges for accountants, CPAs, and tax advisors. This webinar covers critical time deadlines, like-kind requirements, fractional ownership, oil/gas/mineral rights, related party transactions, partnership/LLC scenarios, reverse and improvement exchanges, and how to avoid common pitfalls.
Important Information for Investors Beginning an Exchange
From October 17 – December 31, 2026
If your 1031 exchange is not complete by the due date for your tax return, you may need to file for an extension.
The time frame you have to complete the acquisition of your replacement property ends at midnight on the earlier of: (a) the 180th day after the date you transferred the relinquished property; OR (b) the due date (including extensions) for your income tax return for the taxable year in which the transfer of the relinquished property occurs. (U.S. Treasury Regulations section 1.1031(k)-1(b)(2)).
What does this mean to you?
If your relinquished property sale closes on or after October 17, 2026, your 180-day deadline to acquire replacement property will fall after the common 2026 tax return due date of April 15, 2027.
To have the full 180 days to acquire replacement property, you must file an extension with the IRS for your 2026 tax return and wait to file your return until your exchange is complete.
If you do not file for an extension, you will NOT be able to acquire any replacement property in your exchange after your tax return due date.
Taxpayers may have different tax return due dates. Please consult with your tax advisor to determine your tax return due date, and whether you will need to file for an extension.
👋Meet Sarah Farina, Exchange Associate
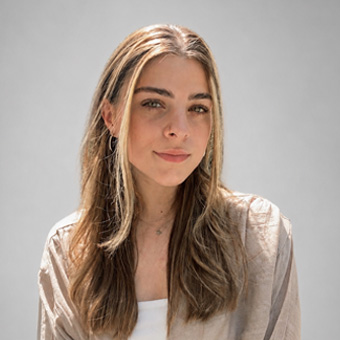
Sarah joined API in 2024 as an Administrative Assistant and has since grown into an Associate role. With a background in real estate and a passion for learning, she has embraced the opportunity to expand her knowledge of 1031 exchanges and support clients throughout the exchange process. Before joining API, Sarah held her real estate license but had never heard of a 1031 exchange. Through API’s extensive training and team support, she has developed a strong understanding of this specialized area of real estate and enjoys helping clients navigate the opportunities exchanges can provide.
Outside of work, Sarah loves to travel, attend music festivals, and spend as much time as possible at the beach during the Long Island’s short summers. ☀️🏖️🎶
What stands out most to Sarah about API?
“My favorite part of working at API is my coworkers, who have become friends during my time here. The support, collaboration, and relationships I’ve built make coming to work every day enjoyable.”
We’re grateful to have Sarah’s dedication, enthusiasm, and commitment to learning as part of Team API.
Disaster Relief Updates
If your exchange has been affected by a disaster, you may qualify for an extension of certain 1031 exchange deadlines. Eligibility depends on the applicable relief and your circumstances.
Recent IRS notices:
Learn more about 1031 disaster relief or contact your exchange counselor and tax advisor.
GET IN TOUCH